How a Rottweiler Premium Climbs With Age
It’s a scenario many of us Rottweiler owners know all too well: you sign up for pet insurance when your furry best friend is a bouncy, healthy puppy, only to find the monthly premiums steadily climbing as they transition into their senior years. This isn't just an illusion; it's a very real financial reality tied directly to the aging process and the increasing health risks our beloved, big-hearted Rottweilers face. This guide will delve into why those premiums creep up, what health challenges contribute to the increase, and what you can do to navigate these rising costs.
The Inevitable Climb of Rottweiler Insurance Premiums
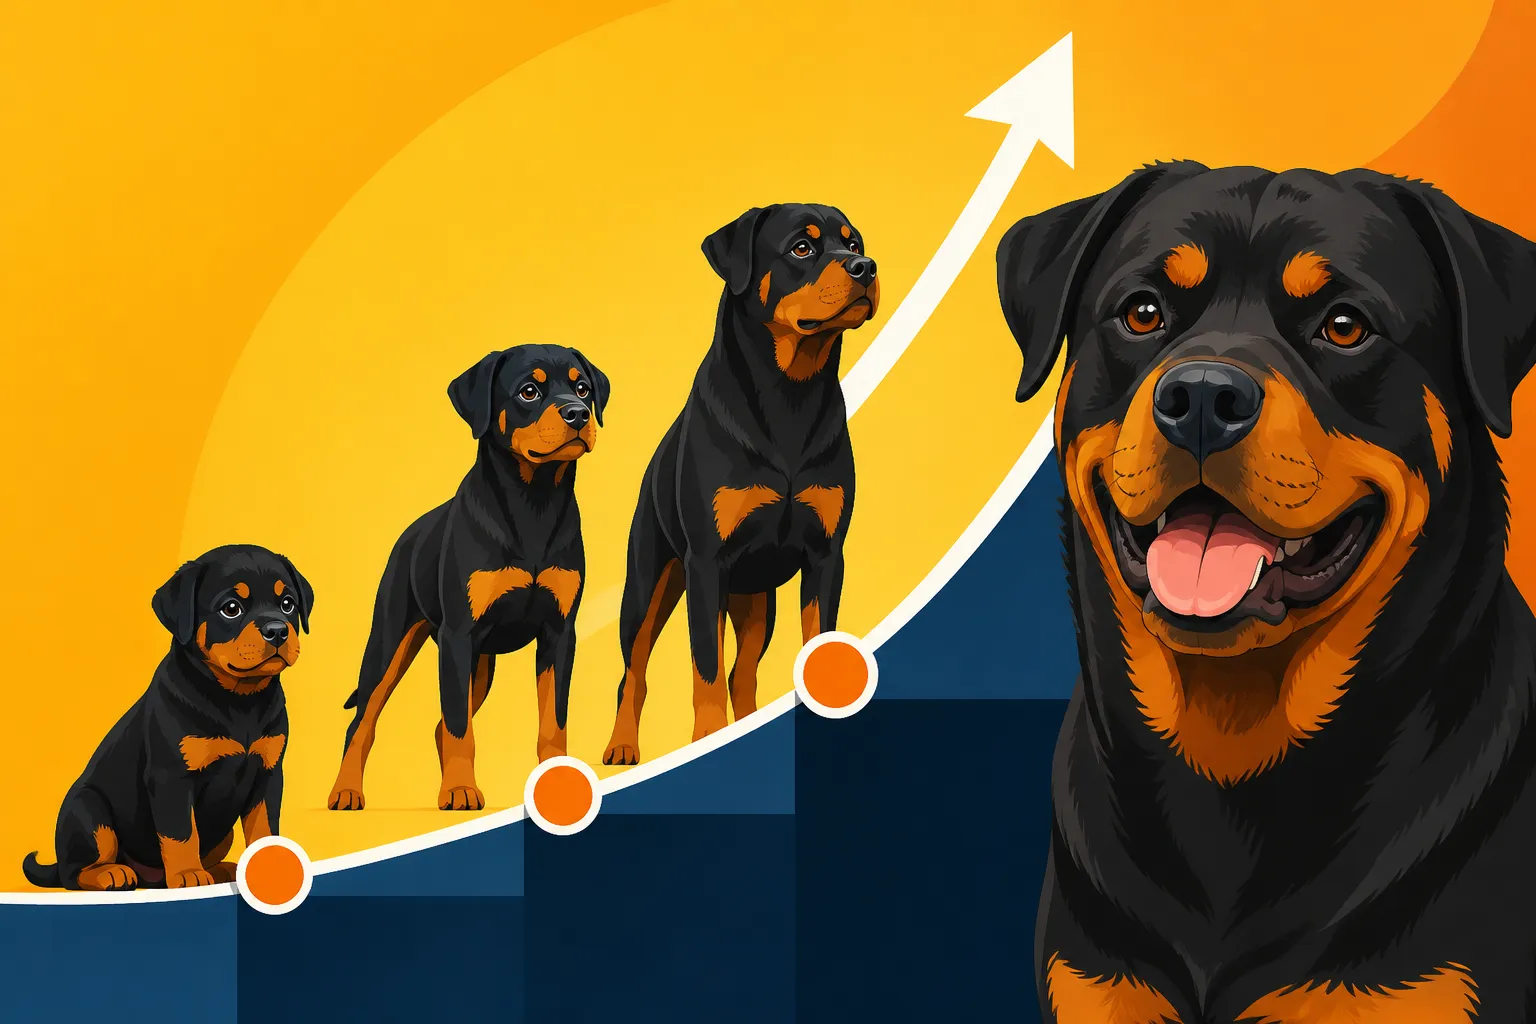
Watching your Rottweiler grow from a clumsy, adorable puppy to a majestic, loyal adult is one of life's greatest joys. But with age, comes a different kind of reality, especially when it comes to their health and, subsequently, the cost of their pet insurance. That monthly premium you pay for a spry two-year-old can look vastly different for an eight-year-old dog, and it's not simply because the insurance company wants more money. There are very logical, albeit sometimes frustrating, reasons behind it.
Why Age is the Biggest Factor
Think about it: just like with humans, the older our dogs get, the higher their chances of developing health issues. For a large breed like a Rottweiler, whose Rottweiler Lifespan and the Eight to Ten Year Average is already shorter than many smaller breeds, this accelerated aging means a higher likelihood of vet visits, diagnostic tests, and treatments. A puppy might need a few vaccinations and a check-up, perhaps a visit for a swallowed toy (we’ve all been there!), but a senior Rottweiler often requires more comprehensive care. They’re more prone to chronic conditions that require ongoing medication, specialized diets, and frequent monitoring. This could mean quarterly blood work, regular X-rays to monitor joint health, or even consultations with specialists. Each of these services comes with a price tag, and insurance companies factor these increased probabilities into their pricing models. They’re simply anticipating the higher number and cost of claims they'll likely process for an older pet.
Understanding Actuarial Risk and Your Rottweiler
Insurance, at its core, is about managing risk. Actuaries – the mathematicians behind insurance pricing – analyze vast amounts of data to predict the likelihood of certain events occurring. When it comes to pet insurance, they look at factors like breed, age, location, and even your pet's past claims history (though some states prohibit using past claims to increase rates, always check your local regulations). For a Rottweiler, this means their predisposition to specific health conditions is already baked into the initial premium. As your Rottweiler ages, the statistical probability of them developing illnesses like cancer, heart disease, or severe arthritis increases significantly.
So, when you see your premium jump, it's because the actuarial tables now show your dog moving into a higher risk category. The older your Rottweiler gets, the closer they are to the age where major health problems statistically become more common and more expensive to treat. This isn't unique to your Rottweiler; it's a broad calculation applied across all insured pets, adjusted for breed-specific risks. The premiums reflect the anticipated rise in both the frequency and the severity of claims. While it can feel unfair when your dog is still bouncing around like a youngster, the numbers simply don’t lie in the long run.
Common Health Issues That Drive Up Costs in Older Rottweilers
Our Rottweilers are incredibly robust dogs, but they are not immune to the wear and tear of time. As they age, certain health challenges become more prevalent, and it’s these conditions that often lead to the increased veterinary expenses that insurance premiums aim to cover. Being aware of these common issues can help you understand why your policy costs might be rising.
Arthritis and Joint Degeneration
This is perhaps one of the most common and costly issues for aging large breeds. Imagine carrying 80 to 130 pounds on four legs for eight to ten years. That's a lot of stress on joints, even for well-structured dogs. Conditions like hip and elbow dysplasia, which can be screened for early in a Rottweiler's life through procedures like Rottweiler Hips and Elbows and the 24-Month Rule, often progress into debilitating arthritis as they age. Even dogs with initially good joint scores can develop arthritis over time due to simple aging and cumulative impact.
Managing arthritis isn't a one-time fix. It typically involves a multi-modal approach: daily non-steroidal anti-inflammatory drugs (NSAIDs), joint supplements (like glucosamine and chondroitin, often available from retailers like Chewy), periodic injections (such as Librela or Adequan), physical therapy, and sometimes even acupuncture or cold laser therapy. Each prescription, supplement, and therapy session adds up, creating ongoing, substantial costs. A visit for a sudden limp might lead to X-rays, medication, and a referral to a veterinary orthopedist, costing hundreds of dollars in a single appointment, with recurring costs thereafter. This long-term management of chronic pain and mobility issues is a significant driver of insurance claims for older Rottweilers, and insurers price accordingly. Managing Arthritis in an Older Rottweiler is a dedicated topic for a reason – it's a big deal.
Increased Cancer Risk
Sadly, cancer is a leading cause of death in Rottweilers, and the risk significantly increases with age. Breeds like ours are particularly susceptible to certain aggressive forms of cancer. Osteosarcoma, the Cancer That Takes Most Rottweilers, a devastating bone cancer, is tragically common in Rottweilers. Other cancers like lymphoma and hemangiosarcoma (a cancer of the blood vessels) also frequently affect older Rottweilers.
Diagnosing cancer can be an extensive and expensive process, involving multiple veterinary visits, blood tests, X-rays, ultrasounds, biopsies, and potentially CT or MRI scans. Once diagnosed, treatment options such as surgery, chemotherapy, and radiation therapy can quickly escalate into thousands, or even tens of thousands, of dollars. For instance, an amputation for osteosarcoma, followed by chemotherapy, can easily reach the upper limits of many insurance policies. While pet insurance provides a crucial safety net for these enormous bills, the sheer likelihood and expense of treating cancer in an aging Rottweiler mean that premiums will naturally reflect this increased risk. This is why having comprehensive coverage for major illnesses is so vital as your Rottweiler matures.
Organ Function Decline and Chronic Conditions
Beyond joints and cancer, older Rottweilers are also more prone to a range of other chronic conditions stemming from declining organ function. These can include kidney disease, liver disease, diabetes, and heart conditions like Dilated Cardiomyopathy in a Rottweiler or Rottweiler Heart Disease and Subaortic Stenosis. Even conditions like Thyroid Disease Behind a Rottweiler's Dull Coat can require lifelong medication and monitoring.
These conditions often require ongoing management: regular blood work to monitor organ function, daily medications, prescription diets (which can be more expensive than regular food, though services like Ollie might offer tailored fresh food options for specific dietary needs), and more frequent vet check-ups. For example, a Rottweiler with kidney disease might need specialized food, subcutaneous fluids at home, and blood tests every few months to track progress. Each of these contributes to a steady stream of veterinary expenses. While not as sudden or dramatic as cancer treatment, the cumulative cost of managing multiple chronic conditions over several years can be substantial, making reliable insurance coverage incredibly valuable as your Rottweiler enters their golden years. Even the risk of Rottweiler Bloat Risk Rising With Age can be a factor, as emergency surgery for this condition is costly and older dogs may have more complications.
How Insurance Companies Adjust Premiums for Aging Rottweilers
It's natural to feel a pang of frustration when your pet insurance premium climbs, especially when you've been a loyal customer for years. However, understanding the mechanics behind these adjustments can shed some light on why it happens. Pet insurance isn't a fixed-rate product for the lifetime of your pet; it's a dynamic agreement that changes as your Rottweiler's risk profile evolves.
Annual Policy Renewals and Rate Reassessment
Unlike some types of insurance that might lock in a rate for several years, pet insurance policies are typically renewed annually. This annual renewal isn't just a formality; it's an opportunity for the insurance company to reassess the risk associated with insuring your particular Rottweiler. Each year, as your Rottweiler gets older, they enter a new age bracket. This new bracket carries a statistically higher probability of illness and injury, as discussed earlier.
During this reassessment, the insurer considers a few key factors. First, the age of your dog is paramount. Second, they'll look at the general health trends for Rottweilers in your area. Have there been advancements in veterinary medicine that make certain treatments more accessible but also more expensive? Are there new prevalence rates for diseases like Rottweiler Cancers Beyond the Bone? While your individual claims history can sometimes influence your premium (depending on your state's regulations and your specific policy terms), the primary driver is almost always the increasing age of your dog and the associated breed-specific risks. It’s a recalculation of odds, and unfortunately for our aging furry friends, those odds tilt towards more medical intervention.
Lifetime Versus Annual Limits
Another crucial aspect to understand is how policy limits impact the real cost of caring for an aging Rottweiler. Most pet insurance policies come with either annual limits, per-condition limits, or sometimes a lifetime limit.
- Annual Limits: These policies cap the total amount the insurer will pay out in a 12-month period, regardless of how many conditions or claims you have. As your Rottweiler ages and potentially develops multiple chronic conditions or a major illness like cancer, you might find yourself hitting this annual limit more frequently or earlier in the policy year. Once the limit is reached, you're responsible for 100% of subsequent veterinary costs until the policy renews.
- Per-Condition Limits: Some policies set a maximum payout for each specific illness or injury over the lifetime of the policy or per year. If your Rottweiler develops chronic arthritis, for example, there might be a $5,000 limit for that specific condition. If the treatment costs exceed that, you pay the rest. This can be particularly impactful for long-term conditions.
- Lifetime Limits: Less common now, these policies cap the total amount an insurer will pay out over the entire life of your pet.
As your Rottweiler ages, the likelihood of needing costly, ongoing treatments for conditions like Rottweiler Obesity and the Load It Adds or other age-related ailments increases the chances of hitting these limits. Even with insurance, you might find yourself paying more out-of-pocket than you expected if you have restrictive limits. This means that while your premium is increasing, the actual value of the coverage might be shrinking if you frequently hit your limits, effectively costing you more overall. This is why it’s important to understand the details of your policy, especially as your Rottweiler matures.
Deductibles, Reimbursement Rates, and Their Impact
While these aren't directly part of your premium increase, your deductible and reimbursement rate play a massive role in your out-of-pocket expenses, which can feel like a rising cost.
- Deductible: This is the amount you pay first before your insurance coverage kicks in. You might have a per-incident deductible (you pay it each time your dog gets sick with a new condition) or an annual deductible (you pay it once per year, no matter how many conditions). As your Rottweiler ages and has more frequent vet visits for various issues, you might find yourself meeting that deductible multiple times if it's per-incident, or simply meeting your annual deductible quickly, which means you're still paying a significant chunk upfront.
- Reimbursement Rate: After your deductible is met, this is the percentage of the remaining bill that the insurance company will pay. Common rates are 70%, 80%, or 90%. If you have an 80% reimbursement rate, you're still paying 20% of every covered bill. For a $5,000 cancer treatment, that's $1,000 out of your pocket, plus your deductible.
As your Rottweiler gets older and medical bills become larger and more frequent, that 10% or 20% co-pay can quickly add up. Sometimes, to manage a rising premium, owners might opt for a higher deductible or a lower reimbursement rate, which brings down the monthly premium but significantly increases the amount they pay out-of-pocket when a claim arises. This is a delicate balance to strike, especially when dealing with the unpredictable and often extensive medical needs of a senior Rottweiler. Understanding these components is key to grasping the true Emergency Vet Bills a Rottweiler Owner Should Expect and how your policy helps to mitigate them.
Strategies to Manage Rising Pet Insurance Costs for Your Senior Rottweiler
It’s tough to see those premiums climb, but it doesn't mean you're powerless. There are proactive steps you can take to manage the financial impact of insuring an aging Rottweiler, ensuring they continue to receive the best possible care without completely breaking the bank.
Reviewing Your Policy Annually
One of the biggest mistakes many pet owners make is simply letting their policy auto-renew without a second glance. This is especially critical as your Rottweiler ages. When that renewal notice comes in, don't just file it away. Take the time to actually read it and compare it with other available options.
Ask yourself:
- Has the premium increased significantly?
- Are the coverage limits still adequate for the types of conditions your senior Rottweiler might face, such as the extensive costs associated with Rottweiler Growth Plates and Why They Close So Late issues evolving into chronic arthritis, or potential cancer treatments?
- Have any new exclusions been added?
- Are there other providers, like Healthy Paws, or local insurers, who might offer more competitive rates or better coverage for senior pets, even with potential pre-existing condition clauses?
It’s worth getting quotes from different companies. While an older dog with existing conditions might find new policies won't cover those specific issues, you might discover a better overall package for new conditions or a more favorable deductible/reimbursement structure. A few hours of research each year could save you hundreds, if not thousands, over the remaining years of your Rottweiler's life.
Considering a Higher Deductible or Lower Reimbursement
If your monthly premium is becoming a real squeeze, adjusting your deductible or reimbursement rate can be a way to bring that number down. This is a trade-off, however, and one that requires careful consideration of your financial situation.
- Higher Deductible: Opting for a higher deductible (e.g., going from $250 to $500 or even $1,000) will almost certainly lower your monthly premium. The catch is that you’ll pay more out-of-pocket before your insurance kicks in for any claim. This strategy works best if you have a robust emergency fund specifically for your Rottweiler’s health needs. If you anticipate smaller, more frequent claims for minor age-related issues, a higher deductible might mean you pay for most of those out of pocket anyway.
- Lower Reimbursement Rate: Similarly, choosing a 70% reimbursement rate instead of 80% or 90% will reduce your monthly premium. But this means you'll be responsible for a larger portion of every veterinary bill. For a major surgery or long-term cancer treatment, that 10% or 20% difference can translate to thousands of dollars.
The key here is to run the numbers. Calculate how much you would save annually on premiums versus how much more you'd pay in the event of a $1,000, $5,000, or even $10,000 vet bill. If you have an established emergency fund for your Rottweiler that can comfortably cover a higher deductible or a larger co-pay, this might be a viable way to keep your monthly payments manageable.
Maintaining Proactive Veterinary Care
While pet insurance is fantastic for unexpected large bills, good old-fashioned preventative care can actually help reduce the overall frequency and severity of health issues, potentially leading to fewer claims and better health for your Rottweiler. Proactive care is especially important for senior dogs.
This includes:
- Regular Vet Check-ups: Don't skip these, especially as your Rottweiler ages. Regular Senior Rottweiler Care After the Age of Seven appointments allow your vet to catch subtle changes early before they become major, costly problems. Early detection of conditions like Rottweiler Heart Disease and Subaortic Stenosis or Thyroid Disease Behind a Rottweiler's Dull Coat can lead to more effective and less invasive treatments.
- Weight Management: Keeping your Rottweiler at a healthy weight is paramount. Rottweiler Obesity and the Load It Adds significantly exacerbates joint problems, increases the risk of diabetes, and can worsen heart conditions. A healthy weight can literally add years to their life and reduce the strain on their body, potentially delaying the onset of costly age-related conditions.
- Appropriate Exercise: Even senior Rottweilers need exercise, but it needs to be tailored to their capabilities. Low-impact activities like swimming or gentle walks can keep muscles strong and joints mobile without excessive stress.
- Dental Care: Good dental hygiene can prevent infections that impact overall health. Regular brushing and professional cleanings can be costly, but the cost of treating severe dental disease, including potential extractions or complications, can be even higher.
Investing in preventative care not only promotes a better quality of life for your Rottweiler but can also help mitigate the need for extensive, costly treatments down the line. It's an investment in their long-term health that can indirectly help manage your overall financial outlay, even with rising insurance premiums.
Building an Emergency Fund
For some Rottweiler owners, especially those with very senior dogs who already have multiple pre-existing conditions that wouldn't be covered by a new policy, self-insuring with a dedicated emergency fund might be a more practical approach. This involves setting aside a specific amount of money each month into a high-yield savings account solely for your Rottweiler’s medical expenses.
The benefits of an emergency fund are clear:
- Flexibility: You have direct access to the funds without waiting for claims processing or worrying about deductibles, reimbursement rates, or coverage limits.
- No Exclusions: Your emergency fund will cover any condition, including pre-existing ones that insurance might exclude.
- Control: You decide how and when the money is spent.
The downside is that you need the discipline to build and maintain the fund, and it takes time to accumulate enough to cover a truly catastrophic event, like a $10,000 cancer treatment. However, if you're consistently paying high premiums for an aging dog and frequently hitting your policy limits, you might find that the money saved on premiums, combined with a consistent savings plan, could build a significant safety net. For many, a hybrid approach works best: good insurance for catastrophic events, and an emergency fund for deductibles, co-pays, and non-covered items. Understanding The Lifetime Cost of One Rottweiler can help you determine how much to aim for in your fund.
| Rottweiler Age | Typical Health Concerns | Average Annual Vet Costs (Estimated, without insurance) | Impact on Insurance Premium |
|---|---|---|---|
| 0-2 years | Vaccinations, spay/neuter, minor accidents, basic puppy care, some early orthopedic screening (hips/elbows). | $500 – $1,500 | Low – Moderate (entry level) |
| 3-6 years | Routine check-ups, dental cleanings, occasional minor injuries/illnesses. | $400 – $800 | Moderate (stable period) |
| 7-9 years | Early arthritis, blood work screening for organ function, increased risk for some cancers, dental disease. | $800 – $2,500+ | High (significant increase) |
| 10+ years | Advanced arthritis, multiple chronic conditions (kidney, heart, thyroid), higher cancer risk, cognitive decline. | $2,000 – $5,000+ (can be much higher with major illness) | Very High (peaks here) |
Note: These are general estimates and actual costs can vary wildly based on location, vet, and individual dog health.
Disclaimer
This article is intended for informational purposes only and does not constitute professional veterinary or financial advice. Always consult with a qualified veterinarian for any health concerns regarding your Rottweiler and a financial advisor for specific insurance or financial planning guidance. Pet insurance policies vary widely, and it is crucial to read your policy documents carefully to understand coverage, limitations, and exclusions.