Why a Rottweiler Raises a Homeowners Premium
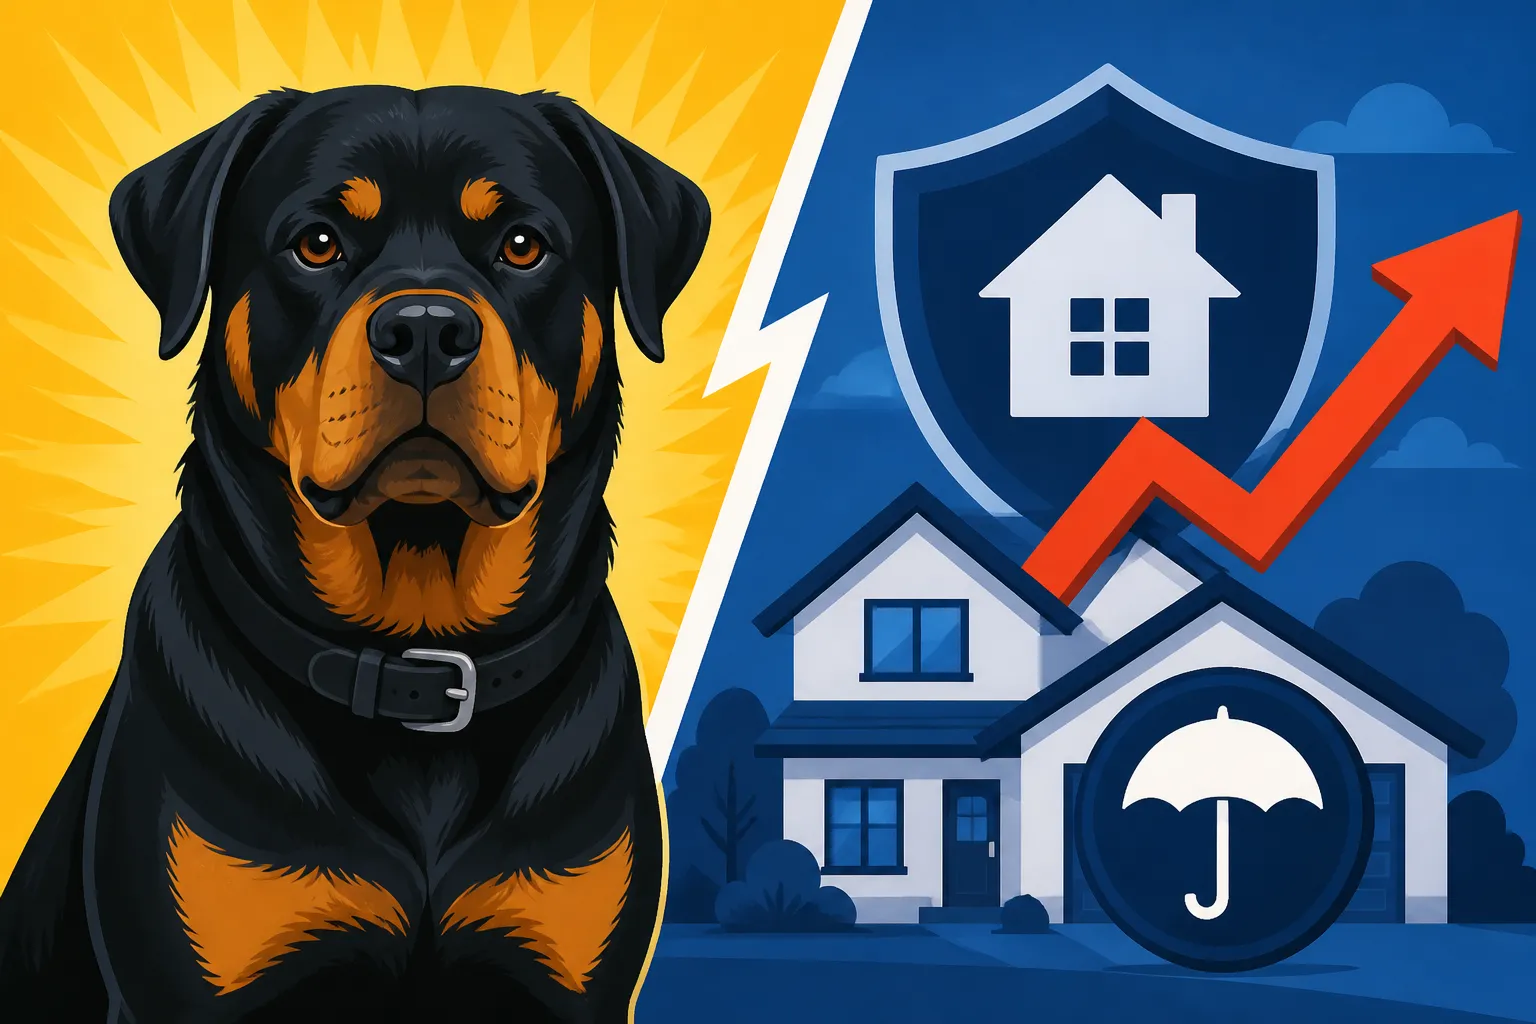
Bringing a magnificent Rottweiler into your home is a joyous occasion, filled with visions of loyal companionship and impressive presence. However, many new or prospective owners quickly discover a frustrating reality: their homeowners insurance premium suddenly skyrockets, or worse, their policy is even threatened with cancellation. This guide is here to shed light on precisely why insurance companies view Rottweilers as a higher risk and how you can navigate the often-confusing landscape of breed-specific restrictions to ensure you and your beloved dog remain adequately covered.
Understanding Breed-Specific Insurance Policies
The moment you mention "Rottweiler" to an insurance agent, you might notice a shift in their tone. It’s not personal, but rather a reflection of industry-wide policies that have developed over decades. Insurance companies, at their core, are in the business of assessing and mitigating risk. When it comes to canine companions, certain breeds, including our beloved Rottweilers, often fall into a category deemed "high-risk." This isn't always fair, nor does it reflect the individual temperament of your well-trained, loving dog, but it's the reality we face.
Why Certain Breeds Are Singled Out
The decision to single out specific breeds like Rottweilers, Pit Bulls, Doberman Pinschers, and others, is a complex one, driven by a combination of historical data, public perception, and legal precedents. Insurers look at statistical data related to dog bite claims. Unfortunately, Rottweilers, due to their size, strength, and past reputation, have historically been involved in a higher proportion of severe bite incidents compared to many other breeds. This doesn't mean every Rottweiler is aggressive; far from it. It simply means that, statistically, when an incident involving one of these powerful breeds does occur, the resulting damage and medical costs tend to be higher. This actuarial data directly impacts how insurance carriers classify the risk associated with owning such a dog, leading to higher premiums or outright breed exclusions.
The Data Behind Higher Premiums
Insurance companies rely heavily on actuarial science to calculate premiums. They collect and analyze vast amounts of data on everything from weather patterns to car accidents to, yes, dog bites. When their data models indicate that a particular variable – in this case, owning a specific dog breed – correlates with an increased likelihood of a costly claim, they adjust their pricing accordingly. For Rottweilers, the concern isn't just the frequency of incidents, but the severity. A bite from a small dog might result in a minor wound, while a bite from a powerful 100-pound Rottweiler can cause significant injury, requiring extensive medical treatment, reconstructive surgery, and potentially leading to long-term disability. These higher potential payouts translate directly into higher premiums for homeowners who choose to live with these breeds. It's a cold, hard financial calculation, often devoid of individual context.
The "Dangerous Dog" Label and Its Impact
The term "dangerous dog" is a loaded one, and it's unfortunate that Rottweilers often find themselves saddled with it, sometimes unfairly, sometimes due to irresponsible ownership in the past. This label isn't just an informal moniker; it can be enshrined in local ordinances and state laws. Many municipalities have breed-specific legislation (BSL) that restricts or even bans certain breeds. While homeowners insurance companies aren't directly enforcing these laws, they are certainly influenced by them. If a city or county considers a Rottweiler "dangerous," insurers in that area are even more likely to view the breed as a heightened liability risk. This means even if your individual Rottweiler is a perfect angel, the pervasive "dangerous dog" stereotype can precede them, impacting your ability to secure affordable coverage and potentially leading to issues like Finding a Carrier After a Rottweiler Denial.
How Homeowners Insurance Companies Assess Risk
When you apply for or renew homeowners insurance, the company isn't just looking at your house; they're looking at your entire household, including your furry family members. Their assessment is a sophisticated process, blending statistics, legal considerations, and often, their own corporate policies. It's a system designed to protect their bottom line, which, while understandable from their perspective, can feel incredibly frustrating for responsible Rottweiler owners.
Actuarial Science and Breed Statistics
As mentioned, actuarial science is the backbone of insurance risk assessment. For dog breeds, this means crunching numbers on bite statistics, injury severity, and the associated medical and legal costs. While you might know your Rottweiler, Brutus, is a gentle giant who wouldn't hurt a fly, the insurance company sees "Rottweiler" and defaults to the aggregate data. This data suggests that breeds like Rottweilers have a higher propensity for claims related to dog bites, and when claims occur, they are often more expensive due to the breed's physical capabilities. These statistics are often based on incidents reported over many years and across various regions, creating a generalized risk profile that applies to all dogs of that breed, regardless of individual training or temperament. It’s an unfortunate reality that even if your Rottweiler is perfectly trained through programs like Rottweiler Obedience Class Fees, the statistical profile can still dictate your premium.
The Role of Local Laws and Ordinances
Beyond the internal data of insurance companies, local laws and ordinances play a significant role. Some cities or even entire states have "one-bite rules," where an owner isn't liable until their dog has bitten someone before. Other areas have strict liability laws, meaning the owner is always responsible for a dog bite, regardless of previous behavior. Furthermore, many locales have breed-specific legislation (BSL), which can range from requiring specific muzzling or containment measures for certain breeds to outright bans. While BSL doesn't directly force insurers to raise rates, it certainly influences their perception of risk. If your community has strict rules regarding Rottweilers, an insurer will likely consider this an additional liability exposure, making them less willing to offer coverage or doing so only at a much higher cost. This patchwork of regulations means that your Rottweiler Insurance From $138 to $264 by State can vary dramatically depending on where you live.
Factors Beyond Breed That Influence Rates
It's not just the breed, though that's often the biggest hurdle. Insurance companies consider several other factors that can influence your premium, both positively and negatively. For instance, if your dog has a known bite history, regardless of breed, your rates will almost certainly increase, or you might be denied coverage altogether. The presence of a fence, especially a secure, tall one suitable for a large dog like a Rottweiler, can sometimes be a mitigating factor, as it demonstrates an effort to prevent unsupervised contact with the public. Your property's specific features, like a large yard with good containment, might also be seen more favorably than a small, unfenced urban property. Even seemingly unrelated things, like your personal claims history (for example, if you've made multiple claims for other issues in the past), can impact how an insurer views your overall risk profile, including the risk associated with your dog.
| Factor | Impact on Premium (Generally) | Notes |
|---|---|---|
| Rottweiler Ownership | High Risk, Higher Premium | Often leads to breed restrictions, higher rates, or denial. Based on aggregate bite statistics and severity. |
| Previous Bite History | Very High Risk, Likely Denial | Any dog with a known bite history, regardless of breed, will face significant challenges. |
| Secure Fencing | Positive/Mitigating | Demonstrates responsible ownership and effort to prevent incidents. Can sometimes lower rates or make coverage possible. [Fencing Requirements That Apply to a Rottweiler |
| "Dangerous Dog" Ordinances | High Risk, Higher Premium | Local laws designating Rottweilers as dangerous increase insurer's perceived liability. |
| Training & Certification | Positive/Mitigating | Proof of Canine Good Citizen (CGC) or advanced training can sometimes help, but not always a guarantee. Helps document [Documenting Rottweiler Training for an Insurer |
| Umbrella Policy | Indirect Cost, Adds Protection | While not directly lowering homeowners insurance, it offers crucial additional liability coverage above and beyond your standard policy. |
| Home Location | Varies | Rural vs. urban, crime rates, and local dog laws can all play a part. |
| Household Claims History | High Risk, Higher Premium | Multiple claims (even unrelated to dogs) can signal higher overall risk to insurers. |
Navigating Breed Restrictions and Finding Coverage
The news that your Rottweiler might complicate your homeowners insurance can be disheartening, but don't despair. It doesn't mean you have to choose between your beloved dog and your home. There are proactive steps you can take and alternative options available to ensure you maintain adequate coverage. It might take a bit more legwork, but protecting your family – two-legged and four-legged alike – is worth the effort.
Companies That Are Rottweiler-Friendly
Not all insurance companies treat Rottweilers the same way. While many have blanket breed bans or significantly increased rates, some carriers are more progressive or offer policies that evaluate dogs on a case-by-case basis rather than by breed alone. It's crucial to shop around and be upfront about owning a Rottweiler from the very first conversation. Asking direct questions about their breed policies is key. Some companies that have historically been more open to breeds often on restricted lists include State Farm, USAA (for military families), and some smaller, local carriers or specialty insurers. Their approach might involve requiring proof of training, a veterinarian's letter attesting to good temperament, or a home visit to assess your dog and containment. You might find that larger, national companies like Geico or Allstate often have stricter breed restrictions, while some regional providers might be more flexible. Always ask for written confirmation of coverage regarding your dog to avoid any nasty surprises should a claim ever arise.
The Importance of Training and Certification
One of the most powerful tools you have as a responsible Rottweiler owner is comprehensive training and certification. A well-trained Rottweiler is a safer, more predictable dog, and proving that can sometimes sway an insurer. Programs like the AKC Canine Good Citizen (CGC) certification, for example, demonstrate that your dog has learned basic manners and is reliably obedient. While a CGC certificate might not magically erase all breed-specific surcharges, it can be a strong mitigating factor that some insurance companies will consider. It shows you've invested time and effort into your dog's behavior, reducing the statistical risk profile. Imagine discussing your insurance needs, and being able to confidently say, "My Rottweiler, Brutus, has his CGC, and we attend advanced obedience classes monthly." This kind of dedication can speak volumes. You might also find value in other forms of training, such as the leash manners that keep your dog from pulling you over or the recall training that prevents them from wandering. It’s about proactive management.
Umbrella Policies as a Safety Net
Even if you find a homeowners insurance policy that covers your Rottweiler, the liability limits on a standard policy might not be sufficient in the event of a severe incident. This is where an umbrella insurance policy becomes incredibly valuable. An umbrella policy provides additional liability coverage above and beyond the limits of your homeowners and auto insurance. For instance, if your homeowners policy covers up to $300,000 in liability, an umbrella policy might add another $1 million or more in coverage. This extra layer of protection is particularly important for owners of breeds commonly associated with higher liability risks, as the costs associated with a severe dog bite can easily exceed standard homeowners limits, leading to potential personal financial ruin. Considering the additional liability a Rottweiler can add, an umbrella policy is often a wise investment, providing peace of mind knowing you're protected against catastrophic claims, including those involving your dog. When looking into this, research how umbrella liability cover truly works.
Minimizing Your Homeowners Insurance Costs
While owning a Rottweiler may present challenges with homeowners insurance, there are strategies you can employ to potentially lower your premiums or at least ensure you're getting the best possible rate. It requires being proactive, organized, and willing to advocate for your responsible pet ownership. Remember, insurance companies are looking for ways to assess and manage risk, and your actions can help demonstrate that you are a low-risk client, even with a powerful dog by your side.
Bundling and Other Discounts
One of the most straightforward ways to reduce insurance costs across the board is to bundle your policies. Many insurers offer significant discounts if you combine your homeowners, auto, and sometimes even other policies like life insurance, with the same company. This can often offset some of the premium increase associated with owning a Rottweiler. Beyond bundling, inquire about other discounts:
- Security Features: Deadbolts, alarm systems, smoke detectors, and fire extinguishers can all earn you small discounts.
- Claims-Free History: A long history without making claims can sometimes lead to lower rates.
- Loyalty Discounts: Staying with the same insurer for many years can also be rewarded.
- New Home Discounts: If your home is newly built or recently renovated, you might qualify for discounts.
- Good Credit Score: Your credit score often plays a role in insurance premium calculations.
Even if the "Rottweiler discount" isn't an option, leveraging every other available discount can help make your total premium more manageable, allowing you to budget for your overall Rottweiler costs.
Documenting Your Rottweiler's Temperament
This point cannot be stressed enough: document, document, document! Your Rottweiler's calm, friendly nature might be evident to everyone who knows them, but an insurance company needs tangible proof. Start early with your Rottweiler puppy and gather records of:
- Obedience Class Certificates: From puppy kindergarten to advanced obedience.
- Canine Good Citizen (CGC) Titles: This is a widely recognized certification for well-behaved dogs. Even a CGC title isn't a silver bullet, it still helps.
- Therapy Dog Certifications: If your Rottweiler is a certified therapy dog, this is incredibly powerful evidence of their stable temperament.
- Veterinary Records: Ask your vet to include notes about your dog's excellent temperament during routine check-ups. A vet’s endorsement can carry significant weight.
- Photos and Videos: While not formal documentation, having visuals of your Rottweiler interacting calmly with children, other animals, or strangers can be helpful context for a human underwriter.
When talking to potential insurers, be prepared to present these documents. The more evidence you have that your Rottweiler is a well-adjusted, non-aggressive member of society, the better your chances of securing favorable coverage. You can even mention that your dog enjoys nutritious meals from brands like Ollie, or that you get their supplies reliably from Chewy, showcasing a well-cared-for pet.
The Long-Term Financial Impact
Owning a Rottweiler involves more than just the initial puppy price or the ongoing food costs; it's a significant financial commitment that extends to every facet of your life, including insurance. The elevated homeowners premium is just one piece of the puzzle. You also need to consider potential increased costs for pet insurance, especially if you want comprehensive coverage for typical Rottweiler health issues like hip and elbow dysplasia, which can be expensive without support from providers like Healthy Paws. Even the cost of your Rottweiler across their lifetime needs careful consideration.
It's vital to factor these potential insurance costs into your budget before you bring a Rottweiler home. Don't assume your current homeowners policy will remain unchanged, or that you'll easily find a new one at the same rate. Planning ahead, researching insurance options for large breeds in your specific area, and budgeting for potentially higher premiums, is a crucial step for any responsible Rottweiler owner. It ensures that the joy of having a Rottweiler isn't overshadowed by unexpected financial burdens or, worse, the terrifying prospect of inadequate insurance protection.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute professional insurance advice. Insurance policies, laws, and rates vary widely by state, region, and individual company. It is essential to consult directly with licensed insurance professionals to discuss your specific needs and obtain personalized quotes.